Business performance H1 2026
Resilient Swiss economy
The conflict in the Middle East has led to a slight increase in inflation due to higher energy prices. However, as medium-term inflationary pressure hardly changed, the Swiss National Bank (SNB) left its policy rate unchanged at zero percent in June 2026. While the European Central Bank raised its key interest rates, the US Federal Reserve kept interest rates constant.
The escalation of the war in Iran is also weighing on the global economy. However, LUKB's base case assumes that the impact on the energy supply remains limited and the rise in inflation is only temporary. Accordingly, moderate global economic growth is expected to continue, even if the economic risks have increased.
The Swiss economy once again proved to be largely resilient and is well positioned due to its comparatively high energy efficiency. If the effects of the conflict remain limited, economic growth of around 1.2 % is expected for 2026.
Start to the new strategy period meeting expectations
LUKB aims to develop into one of the top-five full-service banks in Switzerland by 2030. This ambition can be expressed in a qualitative positioning objective: champion in the Lucerne economic area with strong regional roots and a specialist in Switzerland with the targeted expansion of national business areas in the areas of financing, investing and pension provision.
Quantitatively, the implementation progress of the ‘LUKB30’ strategy is measured against selected financial strategy goals:
- Consolidated profit
- Non-interest income
- Net growth in asset management and asset advisory mandates
- Net growth in the lending business
- Cost-income-ratio
In a largely positive economic environment, LUKB achieved a first half-year result in the new strategy period that matches its strategic orientation.
Notes to the income statement
Significantly improved profitability
LUKB increased operating income by 21.8 million Swiss francs or 6.3 % to 369.2 million Swiss francs in the first half of 2026. This was despite the fact that the previous year's figures were still able to benefit from positive policy rates and the highly volatile market environment.
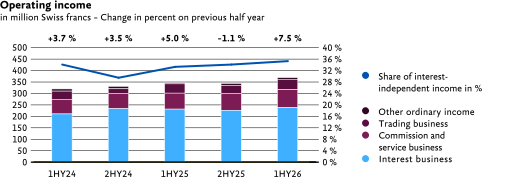
LUKB posted income from interest operations of 238.9 million Swiss francs in the first half of 2026. This represented an increase of 3.1 % over the prior-year period, which was still benefiting from a positive interest rate environment.
At 77.5 million Swiss francs, LUKB's result from the commission business and services exceeded the previous year's figure by 7.7 million Swiss francs or 11.1 % after the first six months of 2026. This growth is primarily attributable to higher portfolio-related income from asset management and asset advisory mandates.
At 45.5 million Swiss francs, the result from trading activities was 4.9 million Swiss francs higher than in the same period in the previous year (+12.1 %). This positive development was primarily driven by structured products, which benefited from calmer financial markets and generally favourable stock market sentiment, particularly in the second quarter of 2026.
At 7.3 million Swiss francs, other ordinary income for the first half of 2026 was 2.0 million Swiss francs higher than in the same period in the previous year (+38.4 %). The main drivers are the equity securities held by the bank. LUKB acted very cautiously when it came to selling these assets, so that hidden reserves increased by a further 3.6 million Swiss francs.
All in all, non-interest income increased by 12.7 % to 130.3 million Swiss francs in the first half of 2026.
Development of operating expenses as planned
At 170.9 million Swiss francs, operating expenses in the first half of 2026 were 5.7 % higher than in the prior-year period. The increase is attributable, among other things, to the implementation of the new ‘LUKB30’ strategy and the increases in working hours required to meet the diverse needs of clients.
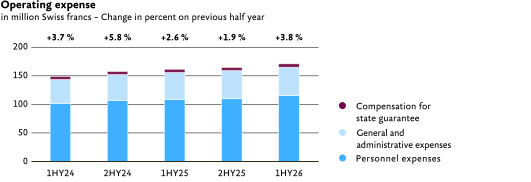
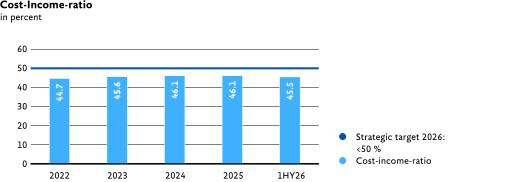
Personnel expenses – the largest expense item at 115.6 million Swiss francs – were 6.9 million Swiss francs higher in the first half of 2026 than in the same period of the previous year (+6.4 %). Headcount increased from 1,206.2 to 1,226.0 FTEs (full-time equivalents). The very positive income development nonetheless enabled the cost-income-ratio to remain at a low level of 45.5 % (31.12.2025: 46.1 %).
Highest half-year consolidated profit since the founding of the bank
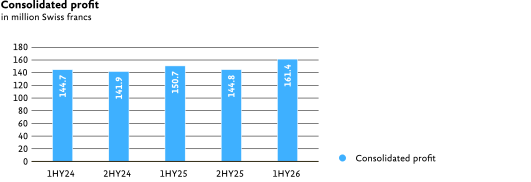
Thanks to the increase in earnings and strict cost discipline, LUKB was able to increase its consolidated profit in the first half of 2026 by 7.1 % in comparison with the corresponding period in the previous year – from 150.7 million Swiss francs to 161.4 million Swiss francs. This is the highest half-year consolidated profit in the history of LUKB.
Notes to the balance sheet
Increase in mandated client deposits
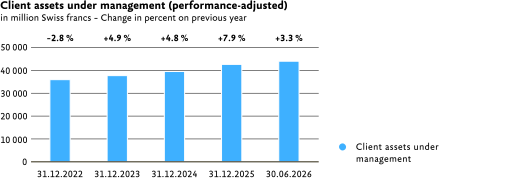
In total, LUKB was managing 43.993 billion Swiss francs of client assets (AuM) as of mid-2026. This is 1.386 billion Swiss francs more than at the end of 2025 (+3.3 %). This growth stems from the increase in net new money of 709 million Swiss francs and the positive performance of 677 million Swiss francs.
Asset management and asset advisory mandates, which are key to sustainable growth in non-interest income, increased by 806.1 million Swiss francs to 18.212 billion Swiss francs in the first half of 2026.
Stable loans to clients
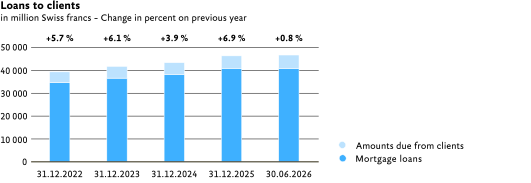
In the middle of 2026, loans to clients at LUKB amounted to a total of 46.717 billion Swiss francs (end of 2025: 46.353 billion Swiss francs), which corresponds to an increase of 0.8 %. Of this total, 40.890 billion Swiss francs are for mortgage loans (end of 2025: 40.918 billion Swiss francs). The increase in lending is therefore solely attributable to amounts due from clients (+392 million Swiss francs). LUKB was deliberately more cautious in the first half of 2026 following the significant growth in lending in 2025 (+6.9 %). Mortgage loans to the price-sensitive client group of real estate companies subject to the Collective Investment Schemes Act (CISA) declined significantly.
Capital base further strengthened
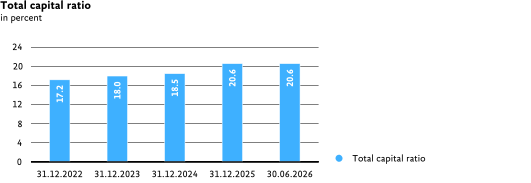
Thanks to the prudent lending policy and the further optimisation of loan collateral, risk-weighted assets (RWA) fell slightly by 68 million Swiss francs in spite of this volume growth. As a result, the CET1 ratio increased to 14.9 % as at 30 June 2026, fulfilling the strategic minimum target of over 14 %. Through targeted management measures, LUKB intends to further increase its profitability in the future while stabilising the CET1 ratio between 14.2 % and 14.9 %. At the end of June 2026, the total capital ratio remained unchanged at 20.6 % and thus at the upper end of the targeted range of 19 % to 21 % (31.12.2025: 20.6 %). This takes into account the fact that as at 30 June 2026, 80 million Swiss francs less can be credited to regulatory capital.
The rating agencies' confirmations also reflect LUKB's solid balance sheet and high level of financial stability: on 23 April 2026, S&P confirmed the credit rating of AA+/Stable/A-1+; on 1 June 2026, MSCI confirmed the ESG risk rating of AA.
Outlook for the second half of 2026
LUKB was able to increase its profitability well above its own targets in the past half-year. This was driven by both interest operations and non-interest income. Even if, as in previous years, profitability in the second half of the year is likely to be lower than in the first six months of the year, we expect consolidated profit to grow. LUKB currently expects consolidated profit for 2026 to be within the target range of 305 to 320 million Swiss francs (2025: 295.5 million Swiss francs). The higher forecast value is offset by other (global) risk factors, the impacts of which are difficult to assess.
‘LUKB30’ financial strategy goals
Strategic targets | 6M 2026 | Targets for 2026 | Targets for 2030 |
Consolidated profit | 161.4 million Swiss francs | 305 bis 320 million Swiss francs1) | > 340 million Swiss francs |
Non-interest income | 130.3 million Swiss francs | > 240 million Swiss francs | > 310 million Swiss francs |
Net growth in advisory and asset management mandates (performance-adjusted) | 806.1 million Swiss francs | > 1.2 billion Swiss francs | > 1.8 billion Swiss francs |
Net growth in lending business (per year) | 0.8 % | 3.5 to 5.5 % | 2.5 to 4 % |
Cost-income-ratio | 45.5 % | < 50 % | < 50 % |
1)Increased as of August 2026 (previously > 295 million Swiss francs